Tag: bitcoiners

  • Reviewing “Defending Bitcoin” by Luke de Wolf

    Reviewing “Defending Bitcoin” by Luke de Wolf

    Bitcoiners in the Nordics and readers of the BTCHEL newsletter The Nordic Node know full well that the Nordics are crazy-full of incredible Bitcoin authors. Kalle Rosenbaum, Ioni Appelberg, Morten Søberg etc, etc.


    When Defending Bitcoin by our in-house security expert and BTCHEL programming master Luke de Wolf was published back in June, we ran a Nordic Node issue and an exclusive Q&A-type interview with him about the book. What was most astonishing was how quickly it had all come together: idea-to-print in about six months. The book has been incredibly successful, with endorsements and mentions by Jeff Booth, Lyn Alden, Lawrence Lepard and more, and has sold about 500 copies!

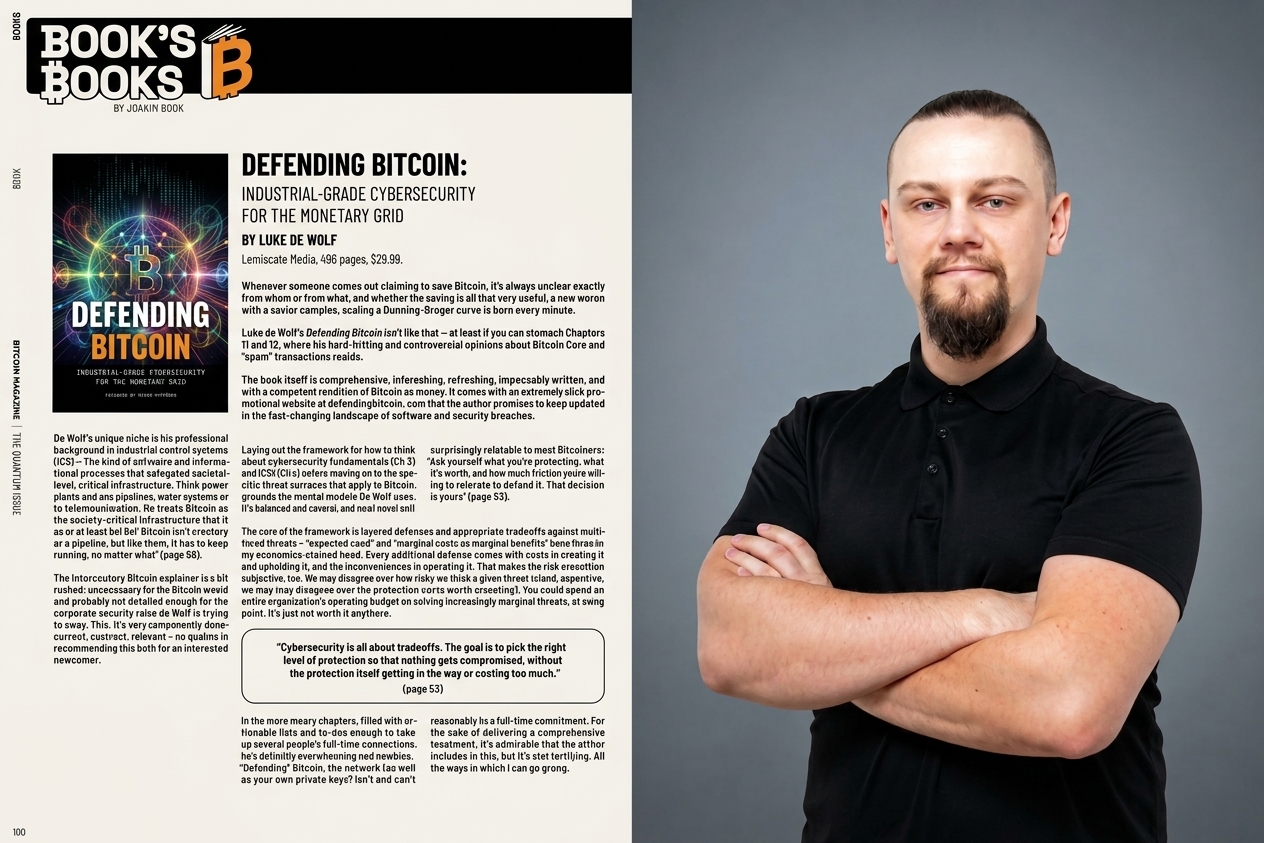
    At the same time, I wrote a (slightly more critical) book review for Bitcoin Magazine’s Print magazine where my book review columns (“Book’s Books”) have more of an elegant and/or ranty feel to them.

    Today, I release that one online — all 1,700 words of it! Bear with me!


    The book is for sale at the Bitcoin Infinity Store (for BTC) and Amazon (dirty fiat) and most online places… if you’re in Lugano for Plan B Forum this week, it’s available there as well!


    This review ran in Bitcoin Magazine Print, in the Quantum Issue (#42), the mentioning of it here was a condition for republishing. It was written in June, at the height of the BIP-110 drama and before the fork failed.
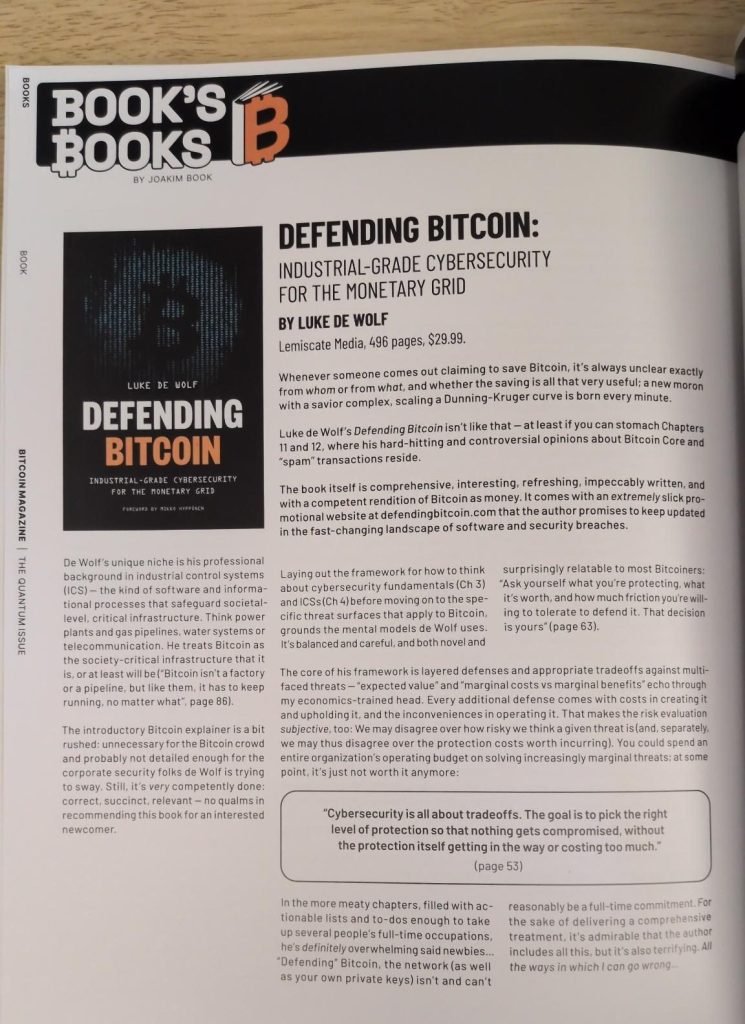


    Whenever someone comes out claiming to save Bitcoin, it’s always unclear exactly from whom or from what, and whether the saving is all that very useful; a new moron with a savior complex, scaling a Dunning-Kruger curve, is born every minute.


    Luke de Wolf’s Defending Bitcoin isn’t like that — at least if you can stomach Chapters 11 and 12, where his hard-hitting and controversial opinions about Bitcoin Core and “spam” transactions reside.


    The book itself is comprehensive, interesting, refreshing, impeccably written, and with a competent rendition of Bitcoin as money. It comes with an extremely slick promotional website at defendingbitcoin.com that the author promises to keep updated in the fast-changing landscape of software and security breaches.

    De Wolf’s unique niche is his professional background in industrial control systems (ICS) — the kind of software and informational processes that safeguard societal-level, critical infrastructure. Think power plants and gas pipelines, water systems or telecommunication. He treats Bitcoin as the society-critical infrastructure that it is, or at least will be (“Bitcoin isn’t a factory or a pipeline, but like them, it has to keep running, no matter what”, page 86).


    The introductory Bitcoin explainer is a bit rushed: unnecessary for the Bitcoin crowd and probably not detailed enough for the corporate security folks de Wolf is trying to sway. Still, it’s very competently done: correct, succinct, relevant — no qualms in recommending this book for an interested newcomer. 


    Laying out the framework for how to think about cybersecurity fundamentals (Ch 3) and ICSs (Ch 4) before moving on to the specific threat surfaces that apply to Bitcoin, grounds the mental models de Wolf uses. It’s balanced and careful, and both novel and surprisingly relatable to most Bitcoiners: “Ask yourself what you’re protecting, what it’s worth, and how much friction you’re willing to tolerate to defend it. That decision is yours” (page 63).

    The core of his framework is layered defenses and appropriate tradeoffs against multifaceted threats — “expected value” and “marginal costs vs marginal benefits” echo through my economics-trained head. Every additional defense comes with costs in creating it and upholding it, and the inconveniences in operating it. That makes the risk evaluation subjective, too: We may disagree over how risky we think a given threat is (and, separately, we may thus disagree over the protection costs worth incurring). You could spend an organization’s entire operating budget on solving increasingly marginal threats; at some point, it’s just not worth it anymore:

    “Cybersecurity is all about tradeoffs. The goal is to pick the right level of protection so that nothing gets compromised, without the protection itself getting in the way or costing too much” (page 53)

    In the more meaty chapters, filled with actionable lists and to-dos enough to take up several people’s full-time occupations, he’s definitely overwhelming said newbies… “Defending” Bitcoin, the network (as well as your own private keys) isn’t and can’t reasonably be a full-time commitment. For the sake of delivering a comprehensive treatment, it’s admirable that the author includes all this, but it’s also terrifying. All the ways in which I can go wrong…

    Hyperbolic Contradictions Won’t Rug the Spammers


    The arguments for either side of the broad schism running through Core-Knots, arbitrary data, mining (template) centralization, and node settings are presented competently and succinctly, only occasionally misleading. To de Wolf’s credit, they’re portrayed miles better than the often performative mudslinging we’re used to from Twitter or conference stages. This is the best possible version of the argument; whatever your stance on quantum, Bitcoin Core, Knots, or nonmonetary data on Bitcoin, Defending Bitcoin is the bright, shining star for considering these themes.

    De Wolf definitely goes too far at times, and he’s repeatedly too shilly for Knots and OCEAN.

    He plays fast and loose with “fungibility”, implying that anything impinging on one UTXO’s interchangeability with another undermines its use as money: “[I]f ‘clean’ Bitcoin spends freely while ‘tainted’ Bitcoin gets stuck in limbo, it stops working as money” (page 207). Gold and fiat, two rival monetary systems, have performed their monetary functions reasonably well, even with quite a lot of obstacles to their global fungibility.

    It’s true that Bitcoin’s don’t trust, verify ethos is meaningfully different than “every other monetary system [where] someone else decides what’s valid.” But it’s hyperbolic to conclude that unless a user runs a node, “everything above it works from a lie” (page 225). There’s a sliding scale of trust, the ease with which you could verify transactions and keys via other means and, in consequence, the vast number of unconnected, somewhat-trusted people around.

    De Wolf’s rundown of Ordinals, NFTs, and the OP_RETURN debacle happens in Chapter 11 (ironically, since some would consider these themes pretty bankrupt…). He admits that these “unwanted” components of Bitcoin are impossible to stop: “It’s always been possible to embed data on Bitcoin” (page 250), that “Bitcoin’s technical properties mean that anyone can embed arbitrary data through known means at any time” (page 263), and that “voluntary filtering alone can’t solve it” (page 263). He nevertheless spends the entire chapter assembling all the reasons nonmonetary data on Bitcoin is bad (“an abuse of a monetary network”, page 265), and recommends users running Knots to ever-so-marginally prevent these transactions relaying across the network: “Relay filtering through Knots is a preventative control that stops spam from propagating through your node” (page 265), and “Mining on a spam-filtering pool or with your own template is the surest way to keep non-financial data out of blocks” (page 264).

    The fact that these efforts are individually expensive and inconvenient, yet practically achieve nothing, should not detract from the noble fight against spam: 

    “In cybersecurity, we don’t stop putting up defenses just because an adversary is hard to stop. It may be impossible to completely stop arbitrary data on Bitcoin, but it’s absolutely possible to slow it down, force it into more difficult or more expensive vectors, and generally to repudiate it as a legitimate use of Bitcoin” (pages 262-63).


    De Wolf paints himself into a corner by admitting repeatedly that arbitrary data is impossible to stop, but that somehow it’s still incredibly important that you — yes, you! — do everything in your power to microscopically close this devastating hack.

    In these more controversial chapters, he straddles the line between dispassionate analyst and activist with a cause. The calls to individual action, no matter how minuscule or impotent, are entirely detached from the careful balancing of costs and benefits from the early portions of the book. “[D]on’t let convenience override the integrity of the system you’re protecting” (page 254), he writes, forgetting that “Low-impact things that don’t matter much aren’t worth considering” (page 55). 

    In critiquing Core changes, he writes that “Bitcoin isn’t an engineering project with a single set of design goals” (page 283) — a statement in stark contrast with the money-only, Bitcoin “maximalism” thesis that runs through the book. The segments attacking “arbitrary data abuse” as “unauthorized non-process traffic flooding the Level 0 network” (page 256) seem pretty clear on what Bitcoin is supposed to be and for whom it works.

    Every sort of counterargument here relies on what Bitcoin intends, what Satoshi meant for Bitcoin to be, and what the ultimate purpose of the network is. We can disagree about the answers to these questions, but the point is that they’re subjective, ambiguous, and mostly unanswerable — meaning that arguments based on an interpretation of what Bitcoin is supposed to be become just that: hypothetical, subjective conjectures.

    In the name of countering spam/inscriptions/unwanted data, getting rid of consensus-valid transactions isn’t worth it. I suspect de Wolf reluctantly understands that — which is why his recommendations boil down to tame, virtue-signaling individual-level actions. Feeling good, not doing (much?) good.

    “Whether BIP 110 specifically is the right vehicle to address arbitrary data remains an open question. I’m clear in my position that arbitrary data is not good for Bitcoin, but changing the consensus rules in a way that breaks existing functionality is a drastic step” (page 293).

    In an altogether characteristic moderation, he relaxes his position with a look to chain splits — the nuclear option making most drastic proposals to counter “spam” not worth it. 

    What annoys me the most is the presumption that arbitrary data is infinitely profitable, thus is (or will) crowd out bitcoin’s monetary use — an existential plague rather than a mostly harmless phenomenon at the, uh, uncharted backwaters of the unfashionable end of the western spiral arm of the Galaxy…

    “Spammers aren’t using Bitcoin as money. Rather, they’re using it as a way to generate value for themselves through the data they embed. It’s worth it to them to pay the fee to get their data inscribed on Bitcoin, and presumably they expect to make their money back” (page 260).

    Call me blue-eyed, I just don’t believe there’s a constant, ever-lasting demand for worthless digital junk. Besides, in manias and bubbles, that sort of leaning-against-the-wind never works — in part because people (irrationally) hoping to profit from peddling nonsense think they’ll profit so much that whatever tiny obstacles you place in their path are but a nuisance. The kicker is that they won’t; thus, the existence of a final sucker.

    The security assessment that the book constitutes, complete with ratings and urgency, is terrifying but also probably long overdue for a leaderless monetary project. It’s admirable that the author created a comprehensive, actionable guide for all the ways you can defend B(b)itcoin. But “Defending” Bitcoin, the network and your own stash, can’t reasonably be a full-time job. What was supposed to be an exit from a part-time investment job outperforming inflation became, implicitly, a part-time technical job staying up to date in software maintenance, running a Lightning node, juggling multisig keys for self-custody assurance, running multiple node implementations, and constructing block templates from your solar-powered BitAxe. 

    The final, optimistic takeaway is that this deep dive made de Wolf see Bitcoin as more resilient than he first supposed. Despite outlining dozens of threats, across AI and quantum and spammers and poor key management and colluding miners and faulty privacy and hostile governments, de Wolf’s “assertion is that Bitcoin has held up remarkably well” (page 383). The downside is that we are its security team.

    It’s a beautiful summary of a painstaking journey, with lots left to do. The repeated emphasis on balancing convenience and security lingers.

    SELECTED QUOTES:

    • “In every system I’ve ever worked on, the most common failure wasn’t a sophisticated attack. It was a human mistake” (pages 389-90).
    • “In 2017, Core had defended Bitcoin’s monetary properties against outside pressure. In 2025, it was telling the community that disagreement would have to express itself somewhere else” (pages 280-81).
    • “Quantum threatens the cryptographic assumptions that protect keys and secure mining. AI threatens the human and economic layer around the protocol, from development and social engineering to mining economics” (page 360).
    • “The protocol doesn’t defend itself. People defend it through the choices they make about what software to run, what development to fund, and what behavior to tolerate” (page 298).
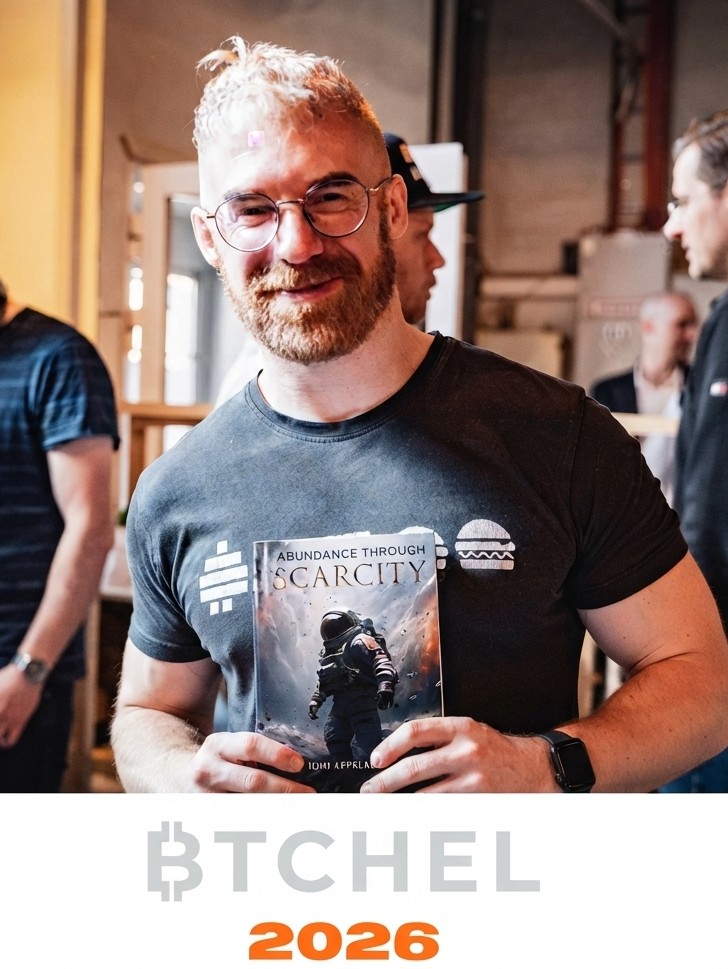
  • Ioni Appelberg and Abundance Through Scarcity: Civilization and Space

    Ioni Appelberg and Abundance Through Scarcity: Civilization and Space

    The first time I read Ioni Appelberg’s great Abundance Through Scarcity was in a D.C. hotel restaurant at the height of the last bull market. It felt celebratory and appropriately lifted my gaze from the depravity of that lost, despicable, politicized city. Money is civilization; civilization is energy; energy propels us forward, technically, and outward, spatially. Our destiny is to become a space-faring nation — or to perish.


    Because I’m different, the times are different, and Ioni actually updated and revamped the book this year (meaning the book itself is different), it’s hard to tell exactly why reading Abundance this time around is an altogether different experience.

    It still has the same lift-your-goddamn-gaze flavor. It’s still obsessed with space and human civilization — quite often the Roman one. It still celebrates money as this insane, improbable, incredible cooperative device between humans. It’s the silent patchwork/bind knitting us together as a species, as a civilization, as the economic collaboration that is the world economy. That the cover is a Bitcoin-clad Astronaut battling a space storm on some far-off planet is strange and unconventional, until you realize that Ioni is obsessed with humans — as a global civilization — becoming a space-faring species.


    But fiat, and its increasingly broken and collapsing institutions, were not meant for the space age. “Fiat currency evolved for a different world,” (p. 227) i.e., our national (often centrally directed) economies, where coordination horizons remain short. For bigger, solar-system endeavors, we need something else:

    “Trying to run a planetary civilization on institution-bound money is like trying to stream video over a fax machine. The infrastructure is not built for what we are trying to do.” (p. 227).


    Then again, Bitcoin with its ten-minute block times would struggle as intergalactic or even galactic money: It’s too slow, the light years of distance between planets and solar systems in our galaxy too vast. Mars, let alone the moon, will probably resort to their own chains.


    The Most Important Thing Satoshi Gave Us


    Scarcity. True, unfakeable, unrivalled scarcity: “scarcity that does not depend on geology or engineering. Mathematical scarcity” (p. 103). Up until Satoshi unleashed Bitcoin on the world, everything digital was infinitely copiable. Nothing (but immediately accessible, material things) was truly ownable. The white paper’s great disruption was

    “…a side effect of making one thing abundant that had previously been scarce: the ability to move value without permission” (p. 150).


    What I saw this time reading the revamped Abundance was an urgency I didn’t notice last time. We are running out of time.


    The rhetorical twists he uses hit like gut punches. Voyager, the hopeful satellites we (“we”) sent out at the peak of the space race, were filled with human language, whale songs, art, and some small collection of the best of what we are. Sent out for an unknown future and improbable meeting, it “keeps going, unchanged, because it was built at a moment when civilization still believed in tomorrow….

    We are the ones who stopped.”


    Abundance is mostly a hopeful book, the way Ioni strikes me as a hopeful, kind soul. It asks the reader to lift their gaze and consider human life and existence on a larger scale, on a longer time frame, doing something more important than your everyday life. And if it hits right, it asks the reader to work diligently for civilization’s success and thriving instead of its decline.  

    It’s also a doomerist, terrifying story — reminding us that what we’re doing here in Bitcoinland is much more important than number-go-up or preserving wealth from the value erosion that is money printing and inflation.


    Bitcoin is here and works, but the wider public remains mostly ignorant of it — if not outright hostile. This is the sort of goldbug/black-pilled/Austrian doomerism I can get behind… fiat can, if not thrive and flourish, muddle through much longer than anyone thinks reasonable.


    This has to work soon, or else (Western) civ is quite rapidly circling the drains.


    Abundance through scarcity sounds like a contradiction — until you realize that some (most?) of the greatest things humanity ever achieved happened by taking away rather than adding; adding by subtraction. Via Negativa. Or, in the overarching metaphor of the book itself: Michelangelo saw — so goes the apocryphal story, anyway — his masterpiece marble sculpture “David” in a piece of inferior block, rejected by everyone else as unsuitable for crafting anything. Just take away everything that isn’t David.


    Toward the very end of the book, Ioni speculates once more on the great filtering and the Fermi paradox (which I was told recently by someone working for NASA, was haphazardly written on a napkin and should be considered accordingly) that “Perhaps the Great Silence is filled with worlds that mastered energy, computation, and intelligence, yet never learned how to endure” (p. 245).

    “The record persists, waiting to see whether it will become the backbone of a conversation across thousands of generations, or a root or in the ruins of another failed ascent” (p. 246).


    This week, you’ll find Ioni giving a lecture on Bitcoin and longevity on Friday exclusively for the OG stage, and be part of the main stage panel session on “Sauna, Meat, and Sun: Bitcoin meets Biohackers” on Saturday.

  • Eric Yakes: BTCHEL Is a “Good Vibes” Conference

    Eric Yakes: BTCHEL Is a “Good Vibes” Conference

    An age ago in Bitcoin years (early 2021), Eric Yakes released The 7th Property: Bitcoin and the Monetary Revolution. It was among the first great “Bitcoin-money” books, a standardized genre where authors thoughtfully consider the role of money in society and history, assess its qualities and characteristics, and only brings in bitcoin and its technobabbling details about halfway through.

    “it wasn’t until I wrote a Bitcoin book that I realized there were so many Bitcoin books out there.”


    Over the years, we’ve been inundated with books like that. Some of great quality, like Lyn Alden’s Broken Money that I — full disclosure — edited, and others of regular trash status.

    The writing-publishing endeavor has, as far as I can tell, cooled down a bit, with the audience more than saturated. To publish successful Bitcoin books a cycle-plus after Yakes, you gotta go big macro (Larry Lepard’s The Big Print), big beginner (Natalie Brunell’s Bitcoin is for Everyone) or very specialized (Leon Wankum’s Digital Real Estate or Aaron van Wirdum’s The Genesis Book — both of which I also worked on).

    The book is almost six years old now, so I wondered what Eric would have done differently today. “There’s a million things I’ve learned since writing the book,” Eric says. His major point with The 7th Property was to give a synopsis of money, banking, and bitcoin from an investor standpoint — the latter being the key demographic.

    “The book did much better than I would have expected at the time.” He described how some books are too heavy on opinion and commentary, and others too lengthy and heavy on the raw, dry facts. You have to strike a balance between expertise and editorializing. “I wanted this to be something that is engaging.”

    He received a lot of mixed feedback: some people thought The 7th Property had “a clear understanding of the problem” and dealt with money and banking in a comprehensive way; others that it was too technical of a book, or too summary. Also, “there was a lot of dentists reaching out… that surprised me.”


    I read a quote to him from the book — “For Bitcoin to compete with the incumbent system, the incumbent’s financial services will need to be replicated in bitcoin” (p. 263) — and wondered if, given the Paper Bitcoin Summer and the last year’s treasury company wave, he stands by that line.


    “I 100% still think that statement is true. Bitcoin is something where the value proposition increases with the amount of capital that enters the system.” By way of a tree analogy, Eric tells me that Bitcoin, like trees searching for sunlight, “is growing toward where the capital is, toward financial markets and the stock market specifically.”


    “The larger bitcoin becomes, the more it can stand on its own.” But until then, building bridges to and integrating with where the capital exists today is how way we make Bitcoin bigger. A lot of people in Bitcoinland have an idealized, black-and-white view of how adoption should proceed. “I don’t think it works like that… we don’t get to choose how adoption happens. That idealized path, it doesn’t exist.”


    One thing that hit me on re-reading the book now, a cycle-and-a-half later, is the emphasis throughout monetary history on trading off trust for efficiency. The book gives two seemingly contradictory positions on the matter:

    • “Digital money will reach an inflection point at which people will need to decide if they will trade trust for efficiency once again. It is my goal to convince enough people that they should not.” (p. 57)
    • “some people do not want to spend the time to be their own custodians, and that is perfectly reasonable but potentially costly” (p. 261)

    “This is where my thinking has developed the most on since writing the book.”


    He clarifies that he thinks that this trade-off warning is mostly intended for fiat. As we’re talking, the Liquid hack/heist has just happened, the Coldcard debacle fresh on everyone’s mind, Lightning service providers getting hacked left, right, and centre. When I mention these token wars, and he says that within Bitcoin, he’s softened his stance there a little: “we’re going through growing pains in software. As long as the tools that create security can be used for attack, we’ll reach a system of far more robust software. We’re going through growing pains… in the long run, I’m not so concerned by it.”

    “This is one way in which owning physical gold at home is safer than owning bitcoin (at least until someone shows up at your house and robs you).” He admits that he hasn’t seen any victory laps from the goldbugs on this either, which is sort of surprising.

    At the end of our talk, I ask about Helsinki and BTCHEL, as Eric will give a keynote on the first day and also spoke at the event last year. He says he’s looking forward to heading out to Finland and that “BTCHEL is a good vibes conference.”

    What he loved about last year was that there “seemed to be a lot of new people,” an audience that’s very different from the usual crowd that attends conferences. The BTCHEL team is working at the marginal forefront of Bitcoin, expanding the circle, reaching new audiences.


    Good vibes indeed. See you all next week!


    BTCHEL2026 CTA tickets, 25-26 September
  • Bitcoin Isn’t Money, Says Representative for the Fiat-Issuing Riksbank

    Bitcoin Isn’t Money, Says Representative for the Fiat-Issuing Riksbank

    No explanation, no analysis, no evidence needed.

    In a speech Wednesday at the Ekonomiska museet in Stockholm, Anna Seim (deputy governor of the Riksbank, Sweden’s central bank) spoke at length about money. Her intricate description of the banking system is good and insightful — though not for the reasons you’d expect — and Bitcoiners can learn a lot from it about the monetary system we’re here to supplant.

    What She Said About Bitcoin Was Both Shocking and Astonishing

    Bitcoin is so unimportant to the establishment that it can be denounced by mere words.

    After briefly describing the three functions of money we’re used to from economics textbooks and Bitcoin books alike — medium of exchange, store of value, unit of account; though, interestingly, she inverts the order by putting store of value at the top — she brushes bitcoin aside in one short sentence.


    Introducing the topic by saying that the digital-money split between private and public institutions is heavily discussed these days, she doesn’t want to talk about bitcoin, “Because it can’t be classified as money according to any of the three criteria above.”

    Anna Seim, “What is money?” Sept 9, 2026 (p. 7/8), speech at Ekonomiska museet in Stockholm.

    Fiat and its money-printing mechanism she then describes expertly and at length: bank money is just made up, created when banks make loans; fiat money is backed by nothing but confidence in the central bank and the wider economy; central banks are tasked with keeping pricing rising “at a moderately high level.”


    Straight from the horse’s mouth:

    “Fiat money has no intrinsic value but derives its value from being accepted as a medium of exchange”


    Money’s underlying “commodity” has gone from gold to confidence; “it contains information about with whom value is to be found, and how much.”

    She brings up an exciting paradox in the use of money, using the age-old economics example (harking back to Adam Smith) of a baker selling bread. He’s paid with money, which functions as evidence that the baker has contributed something valuable to society; he can go on and use the money in exchange for other goods and services.

    While money is a record-keeping device — a record of past value created and supplied (see, for instance, the classic article in monetary economics, ‘Money is Memory’) — it also allows you to forget its history: The next guy in the monetary line doesn’t need to know what good or service the previous person supplied the current holder.

    “The money itself is enough evidence of value.”


    …or at least, that’s how money is supposed to work. In the age of KYC (know-your-customer) and excessive (yet impotent) anti-money laundering efforts, permissioned money in the banking system certainly does not forget its history. (Bitcoin doesn’t really do this either, as evidenced by the recent hacks/heists and the very public movement of funds.)

    What makes money work in the end is all about trust, she admits. “New types of money, new technologies and new issuers mean we must find new ways of establishing and maintaining that trust.”

    True. And that trust is betrayed, repeatedly. Satoshi said so at the start (Letters 10:15-18), and we’re saying so right now.

  • The Quiet Death of the Nordic Bitcoin Treasury Companies

    The Quiet Death of the Nordic Bitcoin Treasury Companies

    When madness and hubris overtook the Bitcoiners and financial markets alike in the summer of 2025, a few strange things happened. 

    First, shares in bitcoin treasury companies (themselves just a pot of financialized bitcoin) started trading way above the value of the coins they represented.


    Second, the financial market equivalent of “the universe abhors a vacuum” rushed in, launching literally hundreds of these companies onto stock markets all over the world.

    Third, in trying to differentiate and maintain their specific value niche, they all tried to raise funds, print shares, and structure convertible debts or other liabilities in order to take advantage of the generational bitcoin bull run. 

    Alas, we know how this story ended.


    When the product you’re selling is overvalued shares, and plunging new investor proceeds from ever-larger securities issuance into ever more bitcoin, two things set an abrupt end to that glorious, orange suitcoiner party:


    a) overvalued shares no longer appeal to investors, and
    b) bitcoin’s price falling.


    It didn’t take long before there was no more financialized equity to extract.
     

    The leading source of bitcoin company balance sheet holdings, BitcoinTreasuries.net, still lists 13 Nordic companies owning bitcoin. 

    We took a closer look and provide a brief overview of the seven most astonishing stories of financial hubris: 


    1. H100 is the largest, most active and well-covered Nordic treasury company. Through acquisitions and changes in leadership recently, it’s been pretty good at garnering attention with its core audience and so we have a fairly good idea of what they’re up to. 

    Bitcointreasuries.net states it holds ₿1,051 (corroborated by its public financial reports), basically unchanged since the treasury company flywheel stopped working in September 2025. Since buying pretty aggressively during the summer (at a blended price of about $115,000), the company has carried massive bitcoin-related losses, having toyed with convertible debts and overplayed its hand.

    After a few acquisitions and changes, H100 is currently trying to merge with Geir Harald Hansen’s company Moonshot (and Never Say Die AS), which should bring the total bitcoin treasure to around ₿3,500. 

    This is achieved via heavy share printing and, in this case, a new, majority owner. The stock is trading today roughly where it was when H100 reverse-merged into Healthy to 100 AS and began its bitcoin journey on public markets; and it’s down about 93% from its June 2025 peak.  

    Per the annual report, by year-end, the company had a 75mSEK convertible loan and about 30mSEK in cash, with no other lien on the bitcoin stash, so there is some financial acrobatics in the firm’s future. (For reference, its bitcoin is now worth about 600mSEK.) Of course, the accounting losses from the past year were roughly half that, which is to be expected if you aggressively buy the peak, and then ride it all the way down. 


    2. Fragbite is a formerly successful gaming company, listed in Stockholm and still with an ongoing operating business in online gaming, acquired its first few bitcoin at $113,000 last summer. Thereafter, it fully YOLO’d into a bitcoin strategy rather late, but still managed to hit the peak at around $120,000.

    The CEO has since resigned, the company holds ₿31.25 (per its Q1, 2026 report, acquired at $114,642) and began doing bitcoin options trading a few months ago. 


    Curiously, the “options trading” operations involve MSTR, Strategy’s common stock, not actual bitcoin or actual bitcoin options.

    (Since it’s for short-term trading and the company hasn’t reported Q2 yet, we can’t know exactly, but per March 31, its balance sheet showed “financial assets” to the tune of about 60% of its bitcoin holdings, so the trading is quite substantial.) 

    Interestingly, Fragbite is not printing shares to pursue its bitcoin strategy. 


    3. B Treasury Capital is a “pure-play” bitcoin company, proudly boasting of a “net sales: 0” post in its financial reporting. Five dudes and a pot of publicly listed bitcoin combined with some liabilities (including a BTC-backed custodian loan and a BTC-denominated convertible debt).

    Refreshingly, it’s one of the few treasury companies that has regularly purchased bitcoin during the spring. It has just closed its preferred share (heavily undersubscribed) for the Swedish market. At year-end, the cost basis for its then ₿166.8 holding was, symbolically, right above the 1-million Swedish Krona (SEK) mark. 

    Since it was listed in July 2025, its shares are down 80%.


    4. Bitcoin Holding Sweden, AB, is a mostly invisible latecomer to the treasury space, having only acquired a small amount (₿2.53) before it suddenly stopped in late November. It markets itself as “Sweden’s upcoming public Bitcoin Treasury company,” suggesting that the company has a future, but alas nothing has been heard from it or its CEO for months.

    Like B Treasury Capital, it ran out of funds before the flywheel got started, having a cost basis above 1-million SEK (now worth only about half that). 


    5. Refine Group is an e-commerce platform that jumped on the bitcoin treasury bandwagon in July last year.

    Having acquired the lordly sum of ₿7, the company threw in the towel in March this year, realizing a loss of about 25%. (The day of the announcement, the share price doubled.)

    Now renamed to Vetted Assets, the company made a wall-art acquisition, has almost doubled revenue, and is trading at about 10x where it was when it launched its bitcoin treasury strategy. 


    6. K33 is a Norwegian-listed crypto research firm, with institutional operations and an excellent industry newsletter (“Ahead of the Curve”).

    Bitcointreasuries.net states K33’s holdings to ₿168, mostly unchanged since the beginning of the strategy apart from a few acquisition transactions during the year that have increased their indirect exposure. From looking over K33’s public investor reports, this is either false or misleading. Per the company’s Q1 quarterly report, K33 holds about 95 bitcoin on its balance sheet plus some “bitcoin exposure” via shares acquired in another company (which, in turn, also only seems to have “exposure,” no real stacking or bitcoin treasury strategy involved). 


    The share is down 75% from its June 2025 peak, and about 40% below where it was when it launched its bitcoin treasury strategy.  


    7. Goobit Group is the holding company behind BTCX, Sweden’s oldest bitcoin exchange. If you’ve been around European conferences in recent years, you may have seen them driving a large, pink, BTC-branded Tesla. 


    Despite not lacking profitability as an exchange, BTCX still hurled itself into a “long-term Bitcoin Treasury strategy, aiming to maximize the company’s bitcoin holdings.” 

    Announced in early August 2025, it ran the typical dilution-as-a-service strategy of issuing shares and buying bitcoin… at the top, only to thereafter go quiet amid plenty of capital destruction.

    The company ostensibly still has the same ₿10.63 it acquired that one time at around $116,000 (plus another coin a few weeks later, bringing the total to 11.7 from Sept 1, 2025). The bitcoin the company acquired last year for long-term holding has now, predictably, been merged into the general business accounts: 

    “in order to strengthen the liquidity. Due to this decision, these 11.35 BTC were restated and moved from intangible fixed assets to inventory.”


    Its diluted shares are down 82% from its local treasury-boost peak.


    Incidentally, BTCX just today received a negative result on its MiCA license from the Swedish financial regulator.  


    The fanfare that accompanied bitcoin treasury companies into the heart of Wall Street and became the poster child for the Paper Bitcoin Summer of 2025, hasn’t been kind to most participants.

    Back then, every few days, there was another Nordic company issuing shares, buying bitcoin, launching a strategy, or engaging in convertible debt offerings. 


    Since the flywheel stopped working in the Autumn of 2025, there have been mostly crickets from the Nordic bitcoin treasury company players. And for good reason: Almost none of the companies have been able to maintain its one-time financialization attempt, and the ones that have exited have done so rather quietly. 

    The bitcoin treasury scene worldwide is comatose. In the Nordics, it’s straight-up dead.

  • Deep Monetary Economics in Oslo’s Satoshi Talks

    Deep Monetary Economics in Oslo’s Satoshi Talks

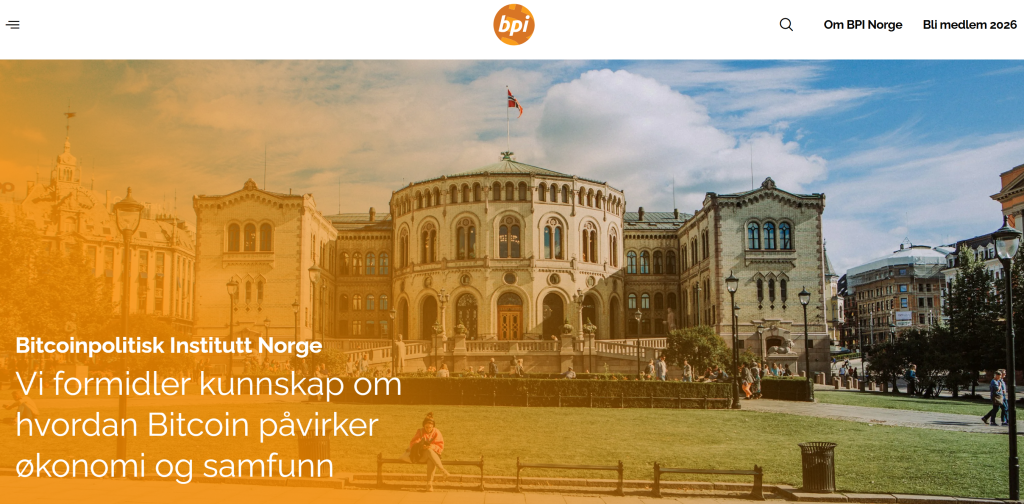
    Bitcoinpolitisk Institutt, or Bitcoin Policy Norway, organized a neat panel session at its events in Oslo’s Litteraturhuset last week. The Satoshi-samtale (“Satoshi talks”) is recorded and released as a podcast, worth listening for a deep dive into the monetary economics of Bitcoin.


    For years, BPI has put on semi-regular events in Oslo and this one doesn’t disappoint. Two guests from the banking system (Jan Ludvig Andreassen, the chief economist at Eika, and Arne Kloster, special adviser to Norges Bank) provided their views, with BPI’s Ole Emil Augland offering critical and, occasionally, quite critical, Bitcoin-oriented commentary.


    Across topics that included the intricacies of the consumer price index, how inflation works through the economy, and how it relates to money printing, the panelists meandered toward what the point and purpose of a monetary system is. At the end, Arne gave us the most succinct conflict of visions involved between bitcoin and fiat:

    “There’s a trade-off between stability and flexibility, and the monetary system we have today is very flexible but it comes with some risks, whereas a monetary system that’s closer to the old-fashioned gold standard is more stable but won’t perhaps contribute to economic growth in the same way.”


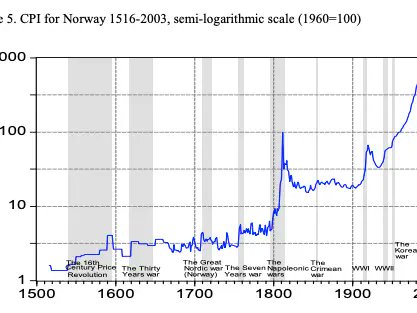
    Here’s the consumer price index graph that Arne presented, based on research and statistics from Norges Bank, and which provided backdrop to the overall conversation:

    Consumer Price Index (CPI), Norway, 1516-2003
    Norway, CPI 1516-2003, long historic time series. Source: Norges Bank.

    Briefly going through that history, Arne suggests that “inflation is, in a way, a phenomenon of war; it’s when lots of money is printed to finance soldiers’ pay, food, canons… war is expensive.”

    And what he brought to weigh on the subject was a very standard remark among the economics profession: What can be even worse than inflation is the price level change variability, “because that makes economic planning difficult.” Stable inflation is manageable since you know that the purchasing power of your money will fall by a particular, credible amount (i.e., the 2% creed), but when the change in money’s worth is unpredictable, money quickly loses its coordinating role and the monetary system turns into chaos.


    Jan Ludvig interjected that household wealth has transformed greatly in the last four decades in Norway, where real estate is concerned. It used to be mostly owned by institutions, but from around 1985 Norway experienced “a historic transfer of value from institutions to households, which also meant that changes in property prices meant so much more than they used to. But they’re not part of the money supply!” Which they probably should, Jan Ludvig suggested.  

    In a beautifully phrased remark by Ole, about the downsides of calculating a consumer price index, we learn that just because a computer improved in raw, objective power (e.g., RAM, memory, speed), statisticians make an error in assuming that the economic value of the item has increased in proportion.

    “They can’t say that ‘yes, the price should be 12,000 instead of 11,000 […] they’re trying to calculate objectively something that is subjective, that is value.”


    You can learn more about Bitcoin Policy Norway (“Bitcoinpolitisk Institutt Norge”) and their work via BPINorge.no.

    Norway's Parliament, Stortinget, overlaid with Bitcoinpolitisk Institutt Norge's frontpage and slogan: Vi formidler kunnskap om hvordan Bitcoin påvirker økonomi og samfunn
    A view of Norway’s parliament, Stortinget, as seen on Bitcoin Policy Norway’s front page.
  • That Nordic Bitcoin Adoption Survey from K33

    That Nordic Bitcoin Adoption Survey from K33

    The Norwegian-listed financial service company K33, focused on serving institutional clients in the Scandinavian crypto world, recently released its annual Nordic Crypto Adoption Survey. The company’s research arm, K33 Research, has released these types of survey-based inquiries into Nordic crypto usage and adoption for a few years now and, as always, they seem very hopeful and optimistic about the Nordic region.

    K33 itself mostly made news waves in the Bitcoin world last year with its somewhat unsuccessful participation in the Paper Bitcoin Summer craze. With some mid-100s BTC on its balance sheet (bitcointreasuries.net says 141, the company’s Q1 investor report, released yesterday, states 168 of BTC “exposure”), mostly acquired in July last year, the company stopped acquiring more coins as BTC/USD prices turned down and the mNAV arbitrage playbook stopped working.


    That is, its financialization effort didn’t pan out, and now the company is pivoting to other market lines, including collateralized loans.

    The report itself, authored by K33’s Head of Research Vetle Lunde, is fairly comprehensive, or at least as well done as can be expected for information-gathering efforts such as these. The 130-page report is filled with graphs and numbers covering crypto users in Finland, Sweden, Denmark, and Norway (plus a public presentation on Iceland, which it covered for the first time this year).

    Surveys, generally speaking, have well-known scientific and statistical problems, particularly in noisy environments where people aren’t exactly eager to answer them. The problem gets orders of magnitude worse in the Bitcoin (and broader crypto) space where privacy is cherished and there’s no upside to confessing and advertising one’s holdings.

    To be polite about it, what the survey finds is not at all representative of the population it is trying to describe.

    Having said that, here are some of the juicier headline results:

    • “2.5 million people in the Nordics own cryptocurrency, equating to 11.1% of the adult population.”
    • “A meaningful share of the Nordic population has owned crypto in the past but no longer does. 6.8% of Norwegians, 7.4% of Swedes, 7.3% of Danes, and 9.2% of Finns report having exited the market.”
    • “More young Nordics now own crypto than directly own stocks, with roughly 1.53 million crypto owners compared to 0.94 million equity owners in comparable age groups.”


    Astonishing Progress for Bitcoin in the Nordics

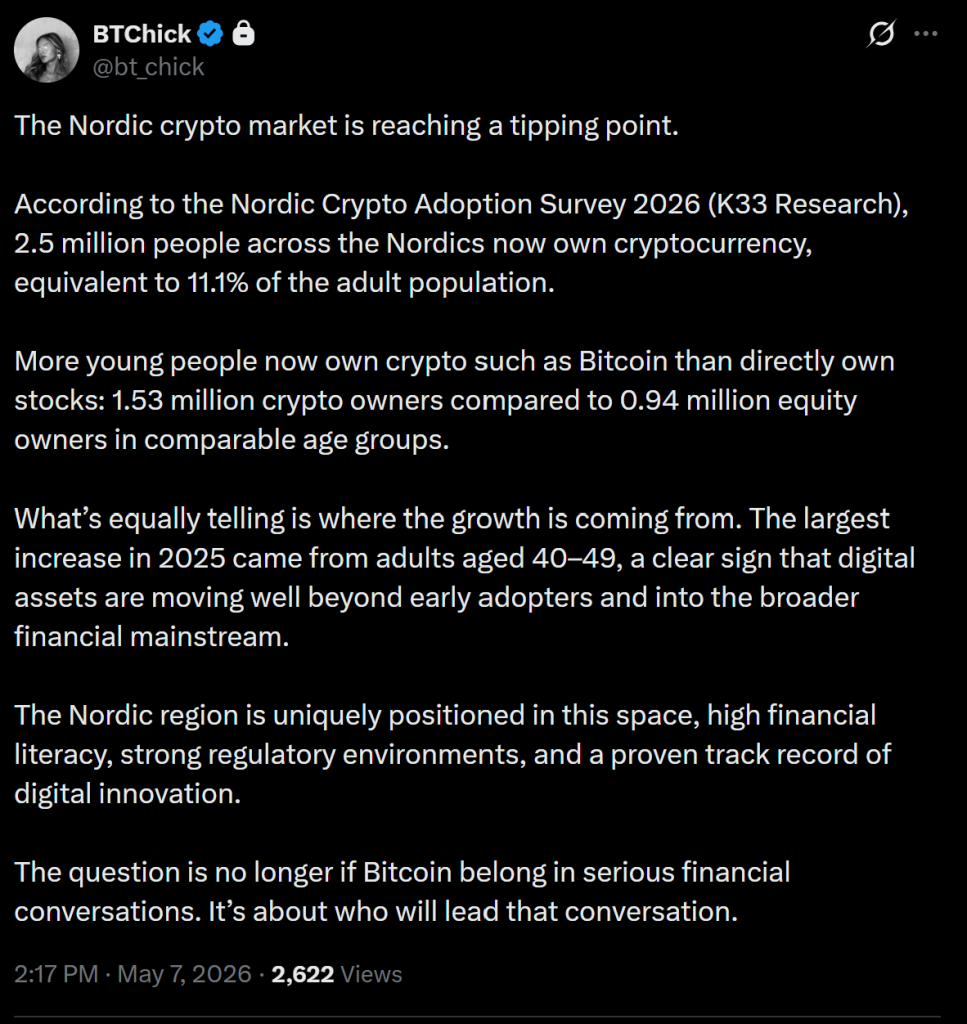
    At a glance, these results look incredible. Here’s BTChick, a Swedish bitcoin influencer, around the time of the report’s release:

    BTChick remarks on Twitter.


    There’s no doubt that there’s some sort of gradual acceptance accompanied by increased adoption and financial flows. Spotted around Stockholm and in public transport in recent weeks are ads by Bitwise, a leading exchange-traded products provider that listed several funds on Nasdaq Stockholm this year, offering crypto exposure “without hassle.” In a talk at the Swedish Bitcoin Symposium 2026, Marco Poblete, Bitwise’s Nordic regional director, presented on the company’s goal of turning “Bitcoin haters into Bitcoin lovers.”


    What the K33 Research reports have going for them is the consistent approach and long-term scope (relative to this industry, anyway). For whatever methodological flaws and faults it contains, comparison across years is pretty neat.; quite a lot of those figures go up and to the right.

    How much of that is capturing a real trajectory rather than statistical noise or a normalization of a new asset class is hard to tell.

    Besides, much murkiness hides behind these impressive headline claims. For example, to engineer the conclusion that “more” young Nordics own crypto than stocks, K33 Research had to explicitly exclude funds and pensions… only the most common and widely owned financial products in e.g., Sweden.

    “We compare self-reported crypto ownership with register-based holdings of listed shares. Figures exclude funds, pensions and some brokerage structures.”


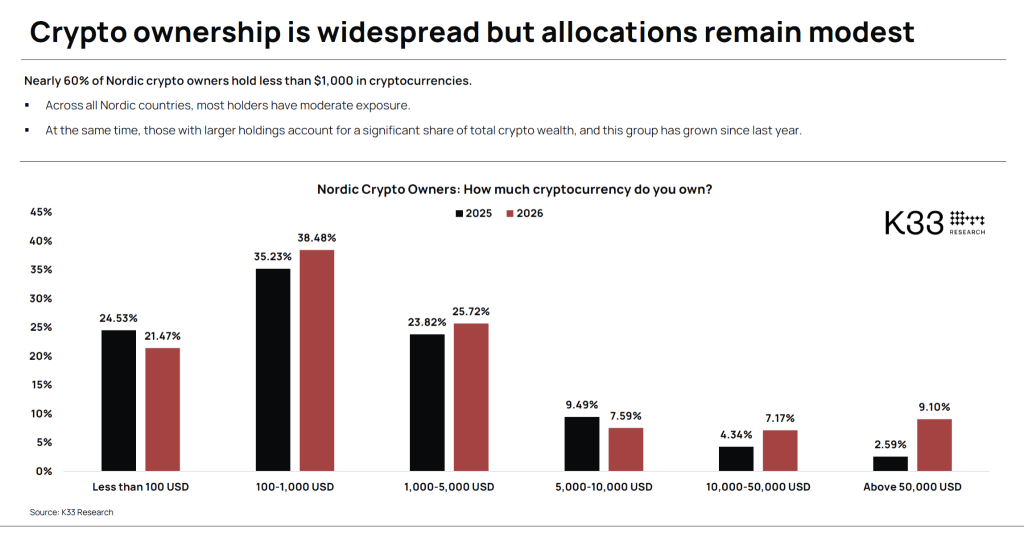
    The 2.5-million figure, or 11% of the Nordic population, is literally unbelievable. Surveying the reported distribution of holdings makes clear how they arrived at that number: Most are trivial (“modest”) holders.

    Nordic Crypto Ownership, per K33 Research’s Nordic Adoption Survey 2026.

    Most of the survey respondents who indicate positive holdings (some 386 people…), report trivial holdings (below 6 million sats). This looks much more like a side-hustle gambling on shitcoins, or some premine allocation, an airdrop receipt, or an online influencer promotion payment than it does consistent, regular stacking by a devoted set of young people embracing a new asset class. And as remarked on above, on the right tail of the distribution, you’re bound to miss a lot of the larger holdings (the “missing-rich” undercoverage problem).

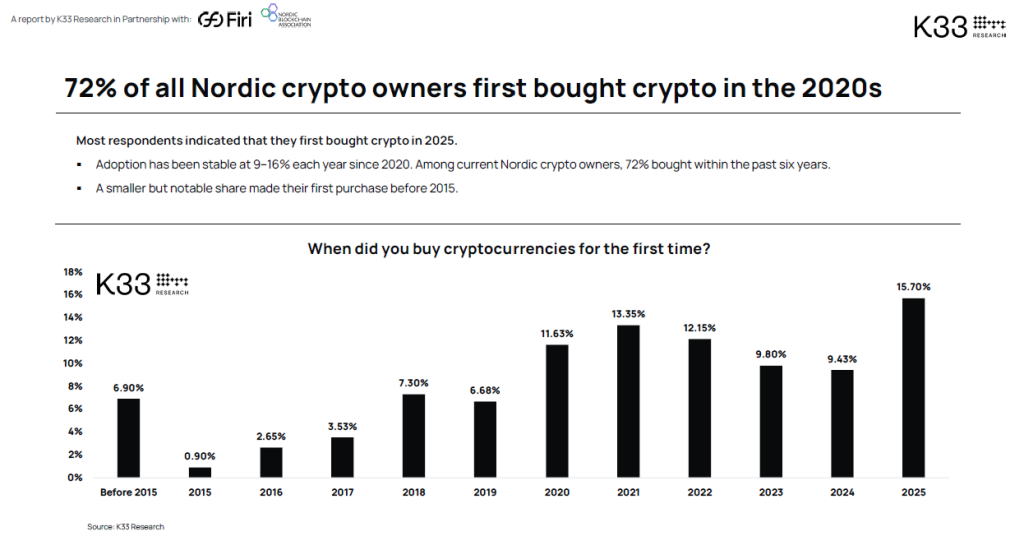
    The least objectionable portion of the survey’s many detailed results is the reported year in which a user first acquired their bitcoin (or “crypto”). The curve passes the sniff test and approximately looks like a bitcoin graph, meaning that it tracks wider information exposure and access.

    When Nordic crypto owners ostensibly acquired their first coins.


    The takeaway from an admirable effort and a hundred-page report is unfortunately that:

    There either isn’t much adoption in the Nordics, in which case this survey is a little pointless, or the survey is missing all the real Bitcoiners, whales, and those with large holdings… in which case the survey is a little pointless.


    In sum, it’s not clear how much new information we can glean from this. A better approach might be to query (and sum up) unique users and activity on the various Nordic exchanges and compare that with holders of e.g, ETPs.


    Some thoughts for next year.