Kategoria: Politics

  • Iceland and Using Inflation as the Release Valve

    Iceland and Using Inflation as the Release Valve

    The Danish economist Lars Christensen recently visited our beloved little nature island, to speak at the Open Day for the Icelandic Financial Services Association. Having observed and analyzed markets for decades — he famously warned about the overheating and imbalances in the economy before the 2008 meltdown — and returning to Iceland again and again, he had a few interesting things to say about this exceptional and exceedingly rich, yet dysfunctional economy.


    Christensen made quite some noise in local media, too, but then spent a full hour on his Makropuls podcast (in Danish) discussing the groundhog-day phenomenon in Icelandic political-economy matters:

    “Iceland isn’t primarily a Nordic economy”
    – Lars Christensen


    For all of us Nordic aficionados, we should realize that the Icelandic economy operates fundamentally differently from the more mature, developed (and diversified!) Nordic economies. We are not the same… and actually not in a good way.


    While a little bit of a spicy take, it’s true in the very nature of what we produce here. This tiny island nation has several elements of all the Nordic countries, but none of the mature, balancing, and stabilizing economic safeguards that make those economies work reasonably well. Iceland is also the (annoyingly rich) little brother who hasn’t figured it out yet. “It’s a globally exposed economy” — tourism, fish, aluminum, data centers — all of which become a modern version of a raw-commodity exporting third-world nation: a complete price taker, walloped around by an ocean of capital inflows and outflows into hot sectors that might not be thriving next year: “It’s an economy where many factors can easily become destabilizing.”


    As Lars explained both in the podcast and in a feature with Morgunblaðið, an Icelandic business news outlet, Iceland really shouldn’t have a money of its own: money wants to be one, so every existing fiat currency fights against monetary gravity for its existence. While all, or most, have some rationale for their arrangements and certainly play some national-identity function, the Icelandic króna has neither:

    “Icelanders very much want currency stability and… I don’t think I’ve ever been to a country with so much love to for their country and so much hate for their own currency as in Iceland.”


    Plus, given the primary extracting nature of the Icelandic economy and the dysfunctional economic institutions — centralized wage negotiations without internalized consequences; a weak, flaccid and always-accommodating central bank — to patch up the boom-and-bust swings that characterize commodity trades, Seðlabanka Íslands is forced to perform too much of the stabilizing, countervailing balancing act.

    Translated from the Vísir interview,

    “Christensen says Denmark has learned from inflation and economic difficulties in previous decades: government, business and unions must take joint responsibility. In Iceland, he sees more conflict between factions and the same disputes repeating themselves. He points out that Icelanders are good at standing together when the national teams compete in handball and football. He would like to see more of that solidarity in the fight against inflation and a greater willingness to understand the perspectives of others.”


    In the podcast episode, Christensen outlined this political-economy conundrum further:

    “What happens in Iceland all the time is the distributional troubles of finding 100 krónur on the street… somebody finds it, and now what? Who gets the gains? Who gets to keep the windfall?”


    Basically: “One sector, be it fishery or aluminum smelters or data centers or tourism, takes off and someone makes a ton of money. The constant political conversation in Iceland becomes: who received something they shouldn’t have had, and how should those things be (re)distributed?”

    “I’m not too worried about the Icelandic economy. It’s doing very well, apart from inflation.” (Vísir)

    …which is sort of the point of his monologue.

    “The Icelandic economy is too small for its own good,” and inflation becomes the central bank’s only way out in facing the aggressive, centralized labor agreements that push for high wage increases unsupported by economic fundamentals. And because there’s been great price inflation in past years, the next round of negotiations include even stronger demands for wages to compensate for the loss of purchasing power. The other Nordic countries fixed this runaway wage-price spiral in the 1970s and 1980s, usually through a combination of local wage determination, pegging the currency, or forcing the unions to internalize the unemployment externality of their too-aggressive actions. But Iceland has had none of that.

    Compare Norway, another Nordic raw commodity exporter. What you do in Norway is take all the oil revenue, collect it in a pot — invested in the oil fund — and take only a small portion into the Norwegian government’s coffers. The extreme rise and fall of the global petroleum business becomes less of a concern in Norway’s economy proper, with the fund and its amassed savings offering a countercyclical buffer. “Norwegians,” explained Christensen, “are able to decouple their great natural resources revenue from what they call onshore Norway.”


    Importantly, the Norwegians counteract the Dutch disease of an overvalued currency hampering their own productive capacities by having this gigantic fund constantly sell kroner to invest in assets denominated in foreign currencies. This, the Icelanders can’t do — or at least, have chosen not to do. It’s not the same singular raw commodity dominating exports year after year (varying between tourism, housing boom, data centers, aluminum, fishery), so levying an appropriate resource tax becomes trickier and less transparent. (Plus, the small-size, rent-seeking nature — some might say “corrupt” — of the political and economic elites, make that arrangement gameable and pretty impossible to achieve.)


    Building up a similar sovereign wealth fund to counteract booms and stabilize or support the economy during busts could be a great way to alleviate Seðlabanka Íslands’ singular response function: inflation as the release valve.
  • Against Mass Surveillance: Stop DAC8

    Against Mass Surveillance: Stop DAC8

    Nineteen-Eighty-Four has never felt closer, with devices that spy on us and powerful algorithmic machines tracking our every move and financial transaction. The noose around our financial freedoms is ever-tightening.


    BULL Bitcoin, a Canadian non-custodial Bitcoin exchange and an Innovators-level sponsor of BTCHEL2026, today launches its Stop DAC8 campaign, designed to counter the 2026 EU Directive that requires European crypto-asset service providers to collect and hand over identity and transaction data for millions of customers. DAC8 came into effect this year, with the first reports expected by 2027. 

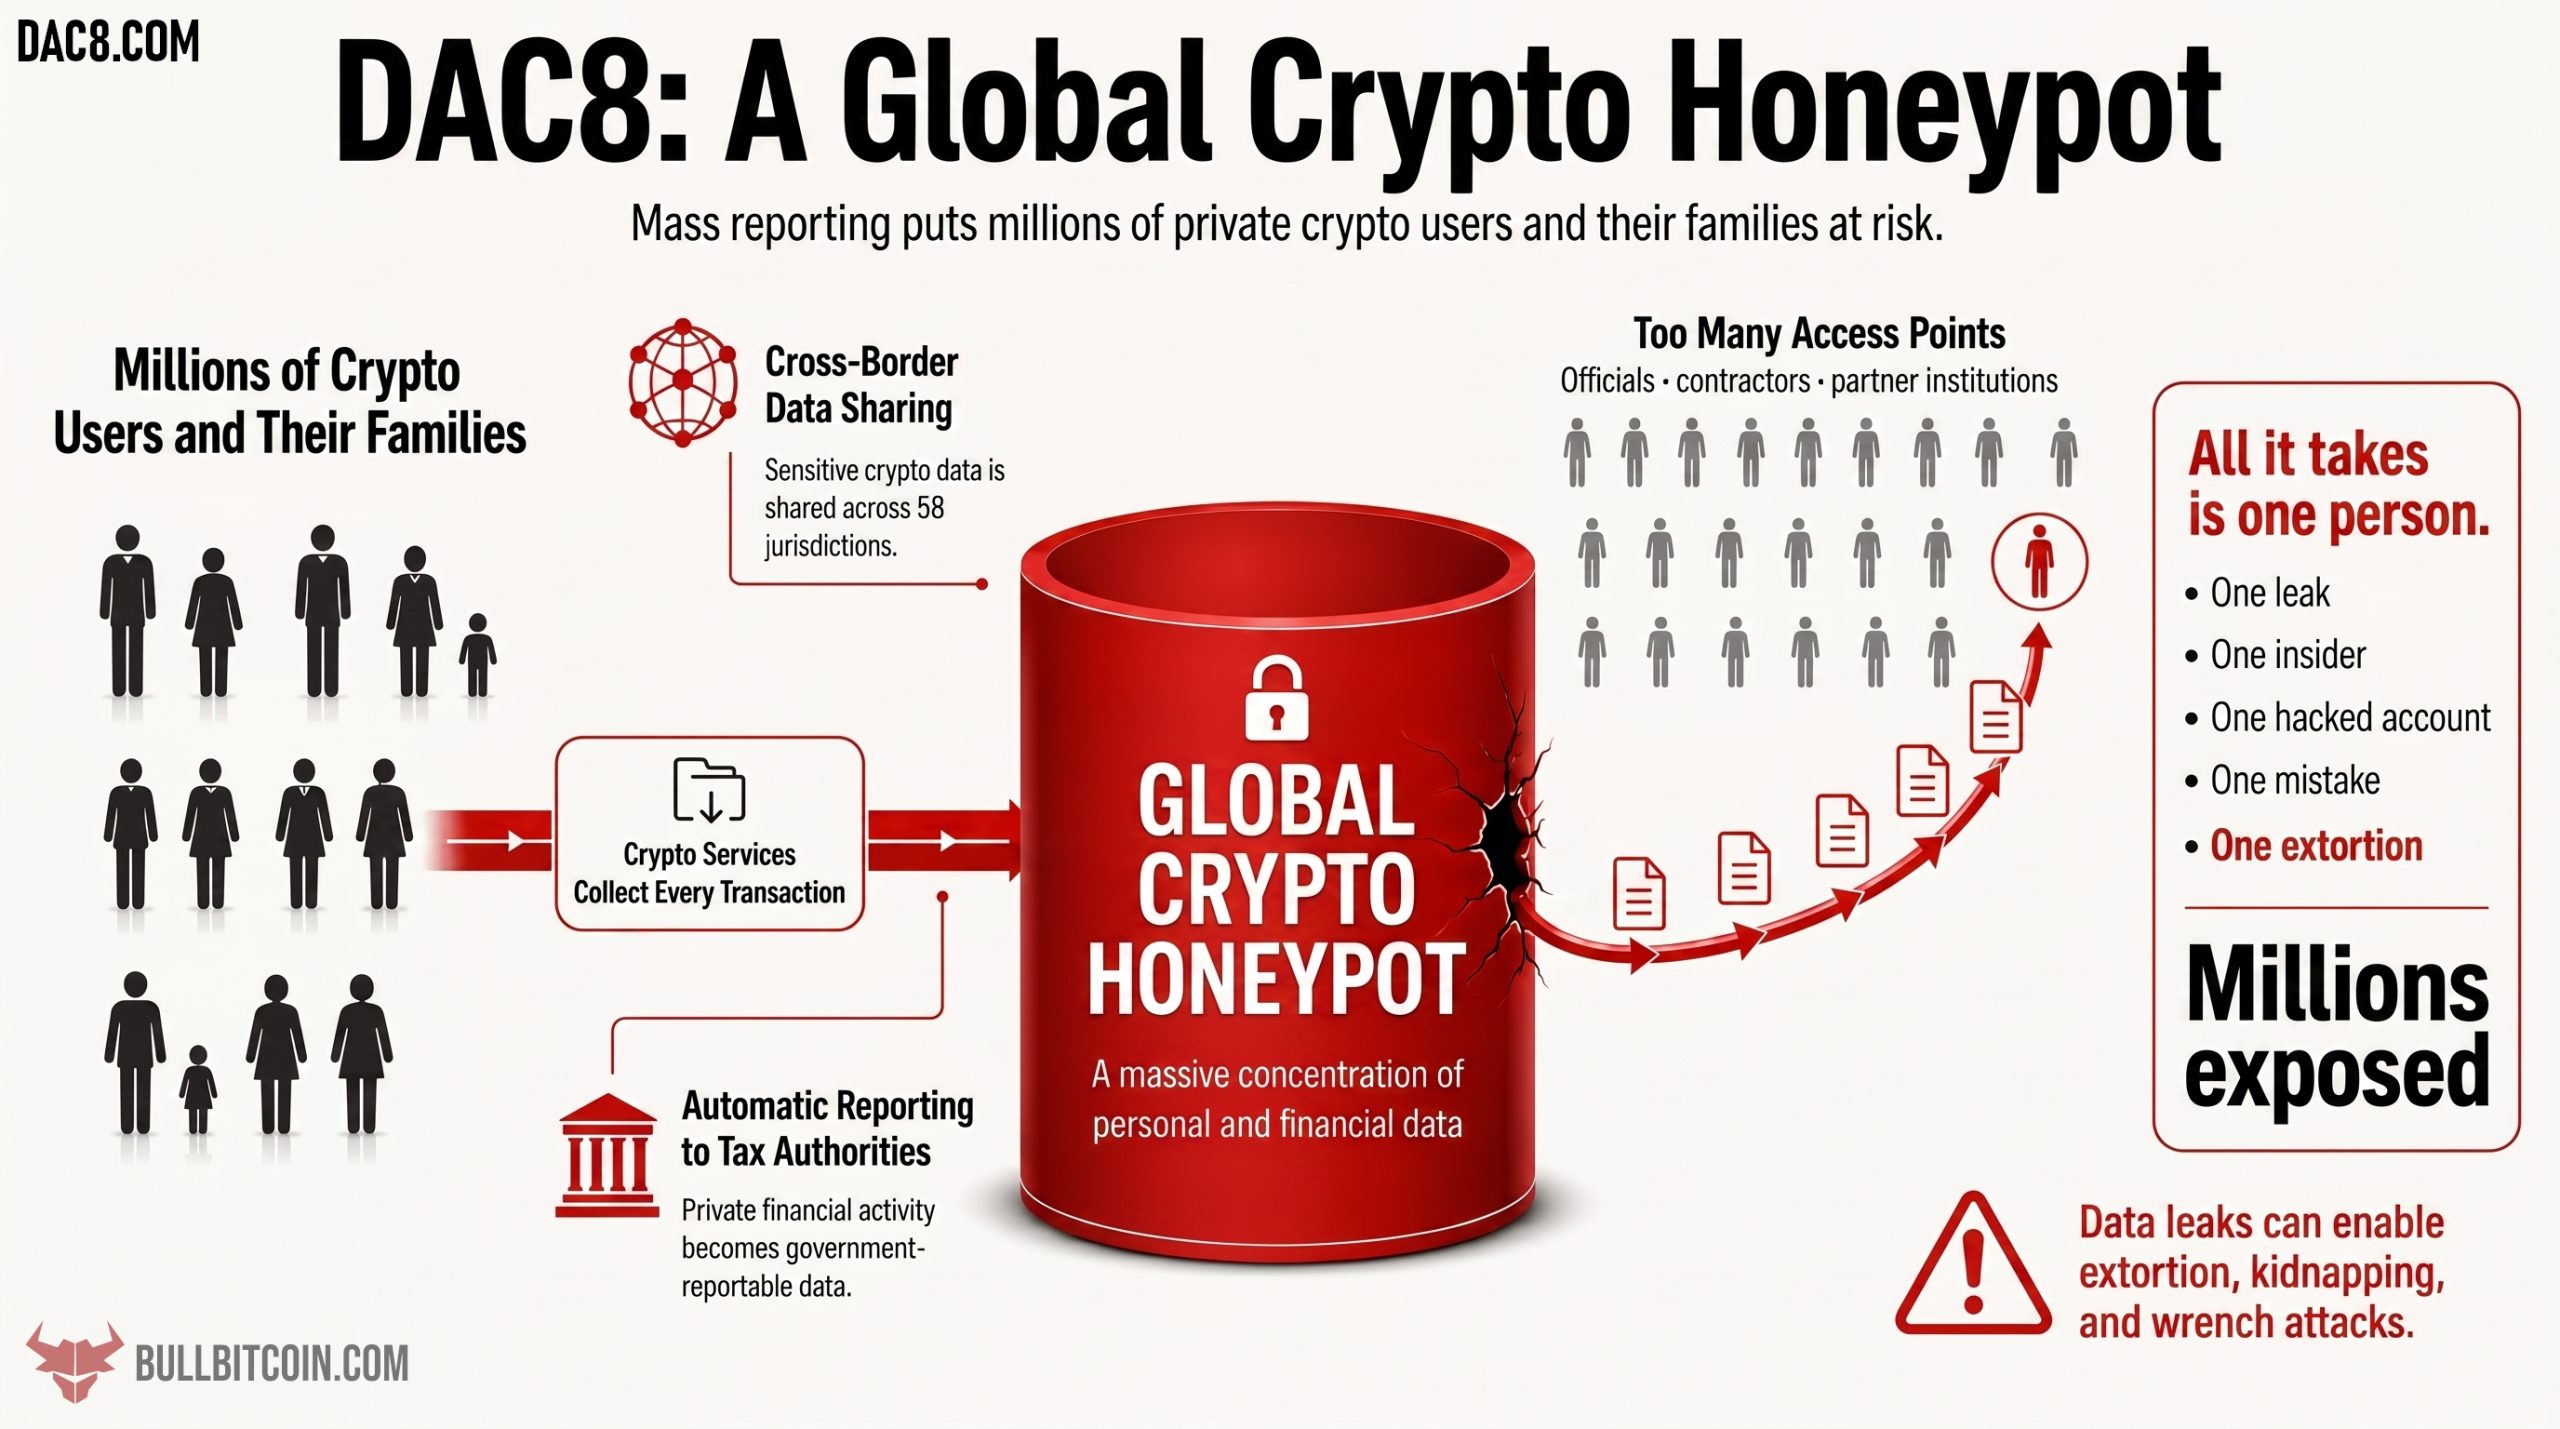
    Under the guise of transparency, the stated purpose of DAC8 is to exchange information between tax authorities, but “the danger lies in the creation of a mass database linking legal identity, home address and transaction history, including transactions that have no relevance whatsoever to taxation,” reads the BULL Bitcoin press release on July 8.  


    Earlier this year, BULL Bitcoin, recently MiCA-licensed through its AMF (LEONOD SARL) entity, filed a summary petition to France’s Conseil d’État, a legal advisor for the executive branch and an administrative court within the French legal system. Bull Bitcoin petitions France’s Conseil d’État to strike down DAC8, which constitutes a dangerous mass surveillance of crypto-assets and their holders. It estimates that between 40 and 135 million Europeans are at physical risk if their crypto data is leaked or abused.


    “DAC8 has transformed the concept of Know Your Customer into Kill Your Customer,” says Francis Pouliot, CEO of Bull Bitcoin.


    Honeypots Are Dangerous and Unnecessary. Don’t Create (More of) Them


    France has been particularly hard hit by attacks against and kidnappings of known personalities in the broader cryptocurrency sphere. When your address and other personal information about you and your family are leaked, together with exact bitcoin (or cryptocurrency) withdrawals in your name, you’re put in particular danger. The microscopic tax and anti-money laundering benefits that may stem from MiCA and DAC8 legislation are completely undermined by the increased threat and danger these informational honeypots pose to civilians.

    “Against a backdrop of daily data leaks and a surge in assaults and kidnappings targeting crypto-asset holders, building such a database endangers the physical safety of millions of holders and their loved ones. The civil servants with access to this data are also put at risk, becoming targets for anyone seeking to obtain it”

    “We’re at a crossroads,” reads the manifesto accompanying the DAC8 website. BULL Bitcoin holds DAC8 to be the “greatest threat to date to the survival of fundamental rights and Bitcoin’s cypherpunk principles.”

    Bull Bitcoin stands as a bulwark: we refuse to be accomplices to this abuse by governments. We refuse to submit without a fight.

    That is why we have launched a legal action to strike down this law.

    The manifesto states that the BULL team is “extremely conscious that we are mandated by law to maintain a honeypot of extremely sensitive private information. In practice, we do everything we can to make sure that this data stays within the walled gardens of our system.”


    Press contact: Theo Mogenet, Managing Director of Bull Bitcoin in Europe (theo@bullbitcoin.com).

    X, LinkedIn, platform app, website

  • Deep Monetary Economics in Oslo’s Satoshi Talks

    Deep Monetary Economics in Oslo’s Satoshi Talks

    Bitcoinpolitisk Institutt, or Bitcoin Policy Norway, organized a neat panel session at its events in Oslo’s Litteraturhuset last week. The Satoshi-samtale (“Satoshi talks”) is recorded and released as a podcast, worth listening for a deep dive into the monetary economics of Bitcoin.


    For years, BPI has put on semi-regular events in Oslo and this one doesn’t disappoint. Two guests from the banking system (Jan Ludvig Andreassen, the chief economist at Eika, and Arne Kloster, special adviser to Norges Bank) provided their views, with BPI’s Ole Emil Augland offering critical and, occasionally, quite critical, Bitcoin-oriented commentary.


    Across topics that included the intricacies of the consumer price index, how inflation works through the economy, and how it relates to money printing, the panelists meandered toward what the point and purpose of a monetary system is. At the end, Arne gave us the most succinct conflict of visions involved between bitcoin and fiat:

    “There’s a trade-off between stability and flexibility, and the monetary system we have today is very flexible but it comes with some risks, whereas a monetary system that’s closer to the old-fashioned gold standard is more stable but won’t perhaps contribute to economic growth in the same way.”


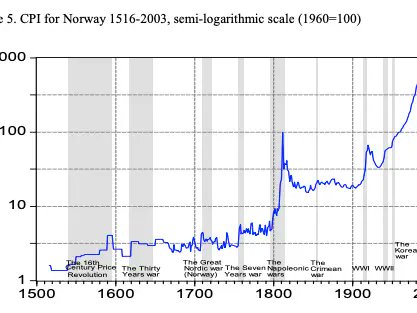
    Here’s the consumer price index graph that Arne presented, based on research and statistics from Norges Bank, and which provided backdrop to the overall conversation:

    Consumer Price Index (CPI), Norway, 1516-2003
    Norway, CPI 1516-2003, long historic time series. Source: Norges Bank.

    Briefly going through that history, Arne suggests that “inflation is, in a way, a phenomenon of war; it’s when lots of money is printed to finance soldiers’ pay, food, canons… war is expensive.”

    And what he brought to weigh on the subject was a very standard remark among the economics profession: What can be even worse than inflation is the price level change variability, “because that makes economic planning difficult.” Stable inflation is manageable since you know that the purchasing power of your money will fall by a particular, credible amount (i.e., the 2% creed), but when the change in money’s worth is unpredictable, money quickly loses its coordinating role and the monetary system turns into chaos.


    Jan Ludvig interjected that household wealth has transformed greatly in the last four decades in Norway, where real estate is concerned. It used to be mostly owned by institutions, but from around 1985 Norway experienced “a historic transfer of value from institutions to households, which also meant that changes in property prices meant so much more than they used to. But they’re not part of the money supply!” Which they probably should, Jan Ludvig suggested.  

    In a beautifully phrased remark by Ole, about the downsides of calculating a consumer price index, we learn that just because a computer improved in raw, objective power (e.g., RAM, memory, speed), statisticians make an error in assuming that the economic value of the item has increased in proportion.

    “They can’t say that ‘yes, the price should be 12,000 instead of 11,000 […] they’re trying to calculate objectively something that is subjective, that is value.”


    You can learn more about Bitcoin Policy Norway (“Bitcoinpolitisk Institutt Norge”) and their work via BPINorge.no.

    Norway's Parliament, Stortinget, overlaid with Bitcoinpolitisk Institutt Norge's frontpage and slogan: Vi formidler kunnskap om hvordan Bitcoin påvirker økonomi og samfunn
    A view of Norway’s parliament, Stortinget, as seen on Bitcoin Policy Norway’s front page.