Avainsana: AI

  • Iceland and Using Inflation as the Release Valve

    Iceland and Using Inflation as the Release Valve

    The Danish economist Lars Christensen recently visited our beloved little nature island, to speak at the Open Day for the Icelandic Financial Services Association. Having observed and analyzed markets for decades — he famously warned about the overheating and imbalances in the economy before the 2008 meltdown — and returning to Iceland again and again, he had a few interesting things to say about this exceptional and exceedingly rich, yet dysfunctional economy.


    Christensen made quite some noise in local media, too, but then spent a full hour on his Makropuls podcast (in Danish) discussing the groundhog-day phenomenon in Icelandic political-economy matters:

    “Iceland isn’t primarily a Nordic economy”
    – Lars Christensen


    For all of us Nordic aficionados, we should realize that the Icelandic economy operates fundamentally differently from the more mature, developed (and diversified!) Nordic economies. We are not the same… and actually not in a good way.


    While a little bit of a spicy take, it’s true in the very nature of what we produce here. This tiny island nation has several elements of all the Nordic countries, but none of the mature, balancing, and stabilizing economic safeguards that make those economies work reasonably well. Iceland is also the (annoyingly rich) little brother who hasn’t figured it out yet. “It’s a globally exposed economy” — tourism, fish, aluminum, data centers — all of which become a modern version of a raw-commodity exporting third-world nation: a complete price taker, walloped around by an ocean of capital inflows and outflows into hot sectors that might not be thriving next year: “It’s an economy where many factors can easily become destabilizing.”


    As Lars explained both in the podcast and in a feature with Morgunblaðið, an Icelandic business news outlet, Iceland really shouldn’t have a money of its own: money wants to be one, so every existing fiat currency fights against monetary gravity for its existence. While all, or most, have some rationale for their arrangements and certainly play some national-identity function, the Icelandic króna has neither:

    “Icelanders very much want currency stability and… I don’t think I’ve ever been to a country with so much love to for their country and so much hate for their own currency as in Iceland.”


    Plus, given the primary extracting nature of the Icelandic economy and the dysfunctional economic institutions — centralized wage negotiations without internalized consequences; a weak, flaccid and always-accommodating central bank — to patch up the boom-and-bust swings that characterize commodity trades, Seðlabanka Íslands is forced to perform too much of the stabilizing, countervailing balancing act.

    Translated from the Vísir interview,

    “Christensen says Denmark has learned from inflation and economic difficulties in previous decades: government, business and unions must take joint responsibility. In Iceland, he sees more conflict between factions and the same disputes repeating themselves. He points out that Icelanders are good at standing together when the national teams compete in handball and football. He would like to see more of that solidarity in the fight against inflation and a greater willingness to understand the perspectives of others.”


    In the podcast episode, Christensen outlined this political-economy conundrum further:

    “What happens in Iceland all the time is the distributional troubles of finding 100 krónur on the street… somebody finds it, and now what? Who gets the gains? Who gets to keep the windfall?”


    Basically: “One sector, be it fishery or aluminum smelters or data centers or tourism, takes off and someone makes a ton of money. The constant political conversation in Iceland becomes: who received something they shouldn’t have had, and how should those things be (re)distributed?”

    “I’m not too worried about the Icelandic economy. It’s doing very well, apart from inflation.” (Vísir)

    …which is sort of the point of his monologue.

    “The Icelandic economy is too small for its own good,” and inflation becomes the central bank’s only way out in facing the aggressive, centralized labor agreements that push for high wage increases unsupported by economic fundamentals. And because there’s been great price inflation in past years, the next round of negotiations include even stronger demands for wages to compensate for the loss of purchasing power. The other Nordic countries fixed this runaway wage-price spiral in the 1970s and 1980s, usually through a combination of local wage determination, pegging the currency, or forcing the unions to internalize the unemployment externality of their too-aggressive actions. But Iceland has had none of that.

    Compare Norway, another Nordic raw commodity exporter. What you do in Norway is take all the oil revenue, collect it in a pot — invested in the oil fund — and take only a small portion into the Norwegian government’s coffers. The extreme rise and fall of the global petroleum business becomes less of a concern in Norway’s economy proper, with the fund and its amassed savings offering a countercyclical buffer. “Norwegians,” explained Christensen, “are able to decouple their great natural resources revenue from what they call onshore Norway.”


    Importantly, the Norwegians counteract the Dutch disease of an overvalued currency hampering their own productive capacities by having this gigantic fund constantly sell kroner to invest in assets denominated in foreign currencies. This, the Icelanders can’t do — or at least, have chosen not to do. It’s not the same singular raw commodity dominating exports year after year (varying between tourism, housing boom, data centers, aluminum, fishery), so levying an appropriate resource tax becomes trickier and less transparent. (Plus, the small-size, rent-seeking nature — some might say “corrupt” — of the political and economic elites, make that arrangement gameable and pretty impossible to achieve.)


    Building up a similar sovereign wealth fund to counteract booms and stabilize or support the economy during busts could be a great way to alleviate Seðlabanka Íslands’ singular response function: inflation as the release valve.
  • Bitcoin Miners Are Becoming AI Companies, But Not In the Way You’ve Heard

    Bitcoin Miners Are Becoming AI Companies, But Not In the Way You’ve Heard

    Every mining conference this year has the same hallway conversation. Someone’s site is being valued at ten times what it was worth as a hashrate operation, and the buyer doesn’t care about hashrate at all. They care about the interconnection agreement.

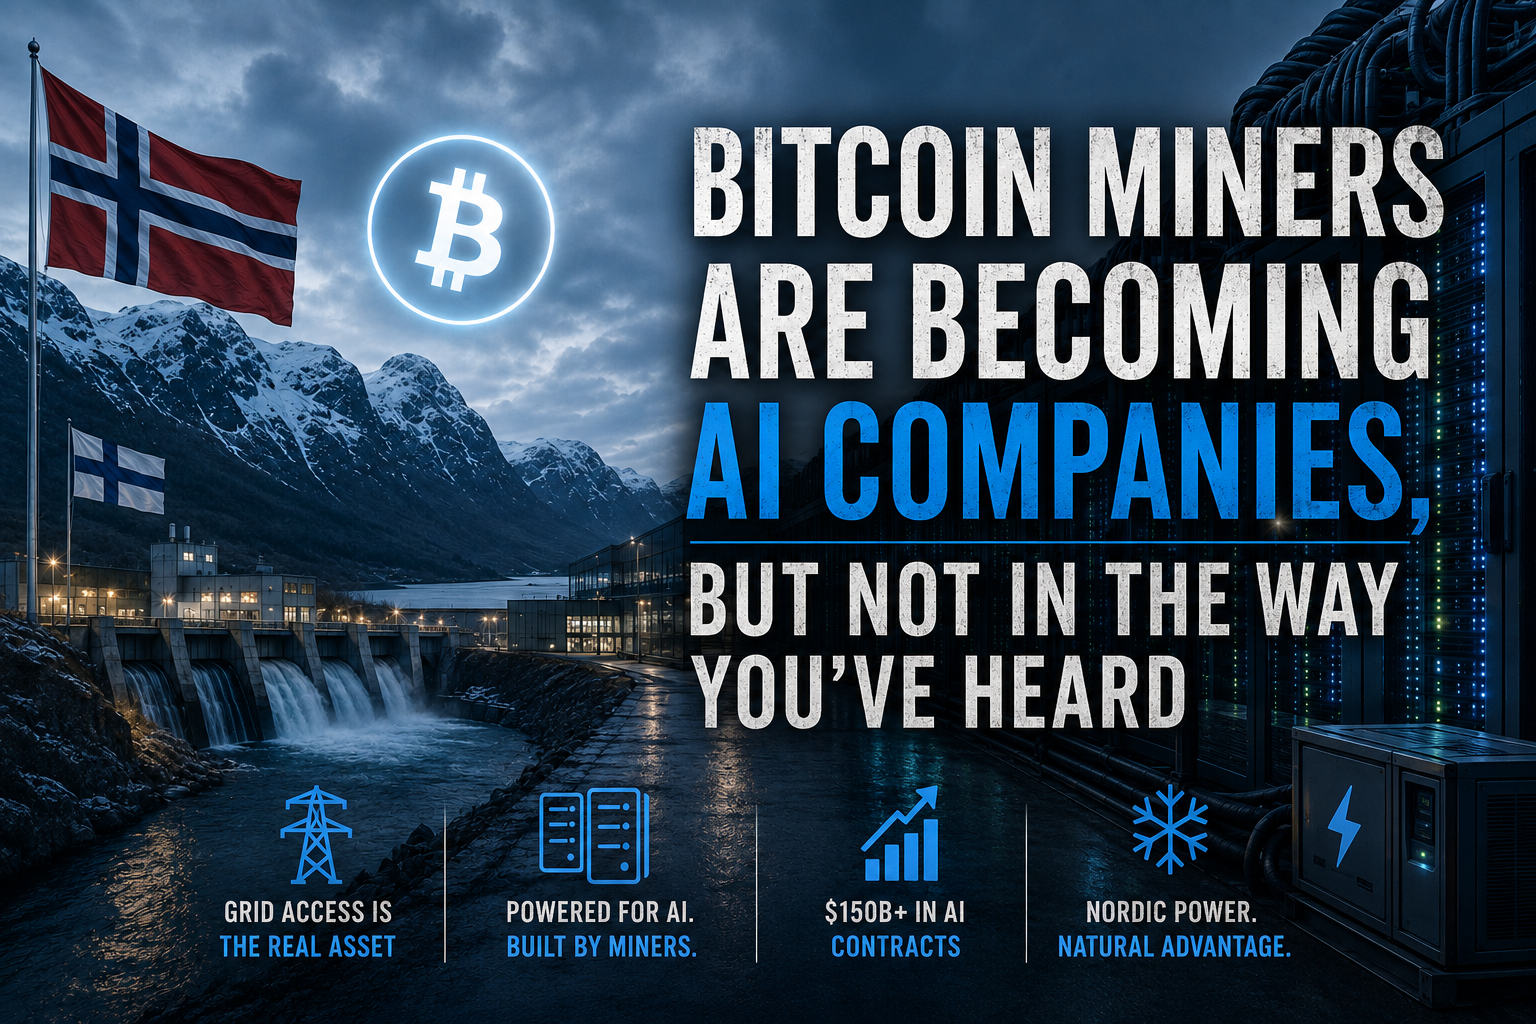
    The numbers behind that conversation are real. According to Bernstein Research, an industry research firm, miners had signed contracts for more than 7.5 gigawatts, valued at $150 billion. Morgan Stanley‘s read is blunter: US data centres need 68 GW between 2026 and 2028, projects under construction and contracted utility capacity cover about 30 GW, and the gap is roughly 38 GW. Bitcoin companies control close to 20 GW with firm grid interconnection already in hand — power that can be delivered years faster than a utility queue that now stretches five to seven years.

    That is the whole trade. Miners spent a decade acquiring the one thing AI cannot buy quickly: permitted, energized, grid-connected land.


    The market has repriced accordingly. Bitcoin is down roughly a quarter this year, from about $87,500 in January to the mid-$60,000. A basket of mining stocks gained more than 50% over the same stretch. CoinShares has miners with secured HPC contracts trading at 12.3x forward revenue (compared to 5.9x for pure-play operators): The market pays double for the AI exposure. At TeraWulf, up over 70%, HPC leasing already overtook mining revenue in the first quarter.

    Diving Into the Data

    Three findings from Byblos Digital corpus are worth putting on the record, including one that cuts against the easy version of this story.

    1. The deals are real and they are concentrated. Separating every partnership and acquisition reported across the VC newsletter corpus produces a clean ledger: IREN × Microsoft at $9.7B; CoreWeave’s $9B acquisition of Core Scientific; Hut 8 × Google; AWS × Cipher Mining, at $5.5B; CoreWeave × Galaxy Digital, at $4.5B for 800MW; Google × TeraWulf, at $1.8B; Cerebras × Digi Power X, at $1.1B. In July, TeraWulf signed a lease with Anthropic, too.
    2. Miners have never raised venture capital, and still don’t. This is the finding that surprised us. Byblos pulled every miner financing event in its corpus back to 2022. Riot, Marathon, Bitfarms, CleanSpark, HIVE, IREN, TeraWulf, Core Scientific: fifteen financings, roughly $6 billion, without a single venture round. Convertible notes, senior notes, share offerings, bitcoin-backed credit lines. That is not a 2026 development: It is how this industry has always funded itself. Anyone telling you miners “can’t attract VC this year” is describing the weather as if it were news.
    3. But venture capital does fund miners, once they stop mining. CoreWeave began as an Ethereum mining operation. Crusoe began as flared-gas Bitcoin mining. Both repositioned to AI compute, and the money changed shape entirely: CoreWeave raised $221M, then $371M, then $3.5B led by NVIDIA and Blackstone, then a $7B Series C. Crusoe went from a $102M seed to a $600M Series D to a $1.375B Series E in January, led by Mubadala with Founders Fund and Bain Capital Ventures. (Note that this sum, totalling $38.8B, comes from VC newsletters, which miss most public company deals. Bernstein counts $150B.)

    Same assets. Same engineers. Same power contracts. Different label, and a completely different capital market opens up.


    A Deeper-Still Dive Into the Data

    Here is the part that doesn’t make it into the bullish write-ups.


    Public bitcoin miners sold a record 32,000 BTC in Q1, 2026. RootstockLabs’ Sam Golden laid out why: weighted-average cash cost to mine sits near $80,000, hashprice has compressed to roughly $28–30 per PH/s/day, and the market was trading bitcoin around $64,000. Operators were selling inventory below production cost to keep the lights on; a subset were selling specifically to fund the pivot into AI compute.


    Golden’s assessment of that trade is worth quoting directly: selling near an $80k cash cost into a $64k market is “one of the most expensive ways to raise a dollar.”

    Read that again, because it reframes the entire narrative. The AI pivot is not being funded by a wave of enthusiastic capital. In a meaningful number of cases, it is funded by selling bitcoin at a loss. Core Scientific liquidated 2,385 BTC (over $200M) in March to fund its transition.

    This is what “miners are becoming AI companies” actually looks like from the inside: a CFO crystallizing a loss on the treasury, surrendering the upside, triggering a taxable event, and doing it at exactly the moment they’d least like to be forced into it.


    …and not everyone can make the trade. The pivot requires a site with real interconnection capacity, a balance sheet that can carry construction capex, and a counterparty willing to sign a 15-year lease. Hut 8 has that. A mid-size operator with 30MW and a hosting agreement does not. The gap between miners being revalued at $15 of enterprise value per watt and those still trading at $2-4 is not a gap in vision. It is a gap in assets.


    The Nordic Angle and What It Means for Bitcoin

    Norway and Finland offer some of the lowest industrial power prices in Europe, backed by hydroelectric and nuclear baseload. This is the stable, long-duration supply AI workloads actually require. Cold-climate cooling is a structural cost advantage, not a marketing line. The region that made sense for mining because power was cheap and the air was free makes sense for AI compute for precisely the same reasons.

    If the pivot works, the network’s hashrate becomes a byproduct of a business that no longer depends on it. Some of us think that’s fine: Hashrate follows price (always has…), and a miner with contracted AI revenue is a miner that doesn’t have to capitulate at the bottom.


    Others think it’s the beginning of something worse: an industry built to secure Bitcoin quietly converting itself into landlords for companies that don’t care about Bitcoin at all. When TeraWulf’s HPC revenue exceeds its mining revenue, what exactly is it a miner of?


    That argument is not settled, and we’re not going to settle it in this article. We are going to have it on stage. BTCHEL 2026 brings the mining and energy operators actually making these calls into one room: the ones who signed hyperscaler leases, the ones who refused, and the ones still deciding. Main-stage mining and energy block, plus the Nordic power conversation that the rest of Europe is about to start having.

    👉 Tickets: early booking rates still available


    Data in this article is supplied by Byblos Digital (byblos.digital). They research fundraising and market insights.

    Check out their beta app: news feed, filtering, and a weekly intelligence brief for people who want curated intel on where the money is moving.